What is the Arc public blockchain? Why is Circle building its own Layer 1?
The Arc public blockchain is an EVM-compatible Layer 1 blockchain developed by Circle, the issuer of USDC. It allows gas fees to be paid directly in USDC and is specifically designed for stablecoin payments, the tokenization of real-world assets, and foreign exchange settlement. Its public mainnet officially launched on September 16, 2026, with founding validators including traditional financial giants such as BlackRock, Visa, Mastercard, and the Depository Trust & Clearing Corporation (DTCC).
How does Arc's positioning differ from that of the general-purpose public blockchains commonly found in the market?
The positioning of this blockchain differs fundamentally from the general-purpose public blockchains commonly found in the market. While Solana aims for a high-throughput retail trading experience and Ethereum seeks to maximize permissionless innovation, Arc has defined itself as a “settlement network” from day one. Circle officially stated inProduct DescriptionIn China, it is referred to as the “economic operating system of the Internet,” with its target applications being payments, clearing, foreign exchange, and capital markets—rather than on-chain speculation.
Understanding this difference in positioning is essential for evaluating all Arc-related opportunities. Below, we’ll first break down Circle’s true motivations for building its own blockchain, then examine the infrastructure design, the current state of the ecosystem, the token’s status, and the actual cost of participation, layer by layer.
What's the problem with Circle issuing USDC on Ethereum?
Circle’s primary motivation for building its own blockchain was the “cost of holding two currencies.” For businesses to use USDC on Ethereum or Solana, in addition to holding USDC itself, they must also purchase and hold ETH or SOL to cover transaction fees. For a cross-border e-commerce company or payment service provider that only wants to accept and make payments in U.S. dollars, this effectively forces them to maintain a highly volatile cryptocurrency position on their balance sheet—a situation that is difficult to justify from both a financial and compliance perspective.
Arc’s solution is to make USDC a native gas token. All fees are denominated in U.S. dollars, allowing businesses to record their on-chain costs directly on their income statements without having to bear currency price risk to cover transaction fees. While this may seem like merely an optimization of the user experience, it actually removes a structural barrier to institutional adoption of stablecoin settlements.
Why can't traditional clearinghouses accept block reorganizations?
The second reason is more technical but has a more profound impact. On chains like Ethereum or Bitcoin, having a transaction included in a block does not equate to final confirmation: if a longer chain emerges on the network, the original block will be replaced—this is known as a block reorganization. For retail investors, simply waiting for a few more blocks to be confirmed is sufficient; but for an institution like the DTCC, which processes trillions of dollars in securities settlements daily, the fact that “settlements can still be reversed after they’ve been finalized” is untenable from both a legal and accounting perspective.
Arc employs a consensus design with deterministic finality; once a transaction has been signed by two-thirds of the validators, it is finalized and cannot be altered. This eliminates the risk of reorganization, but at the cost of requiring a finite set of validators whose identities are known in advance. Virtually all design trade-offs across the entire chain stem from this fundamental principle.
What is Circle's third motive?
The third motivation is control. Operating on someone else’s blockchain means that hard forks of the underlying protocol, MEV congestion, soaring gas fees, and even changes in governance direction are all beyond Circle’s control. USDC currently has a market capitalization of approximately $65 billion, accounting for about 24% of the stablecoin market, second only to Tether’s approximately $164.8 billion. When an asset reaches this scale, entrusting its settlement lifeline to infrastructure beyond one’s control is, in itself, an operational risk.
It is worth noting that Circle has not withdrawn USDC from other blockchains. Arc is an addition, not a replacement. USDC continues to circulate on more than 20 networks; Arc is targeting the entirely new, previously off-chain business of institutional-grade settlement.
How Can Retail Investors Actually Participate in Arc? Entry Costs and the Process
The Arc mainnet is now live, and the barrier to entry is actually lower than for most new blockchains: USDC itself serves as gas, so you don’t need to buy the native token first to get started; once the official cross-chain bridge goes live, the premium will disappear. What you really need to be careful about isn’t the cost of entry, but what to buy once you’re in.
What is the correct way to obtain USDC on the Arc chain?
If you already have USDC, the process is simpler than most tutorials suggest: Switch your wallet to Arc, use the built-in cross-chain feature to transfer directly from chains like Ethereum, BNB Chain, or Solana—it’s done with a single click. Since USDC itself serves as Arc’s gas, it’s available for use immediately upon arrival—no need to set aside separate gas tokens or figure out which cross-chain bridge to use.
If your wallet does not have Arc built-in, fill in the following fields to add it manually: Network Name: Arc, Chain ID: 5042, Gas Token: USDC, RPC Node: rpc.mainnet.arc.io. Be sure to double-check the chain ID, as there is another ARC Mainnet chain with the same name but a different chain ID—1243—which is unrelated to Circle.
As for the premium that existed before the mainnet launch, it no longer serves as a useful reference. At that time, the Arc version of USDC could only be obtained through Unstable, an independent third-party OTC market, where the quoted price at one point approached a 1.8-to-1 ratio plus a 3% fee. As soon as the official cross-chain bridge opened, arbitrageers wiped out the spread—an inevitable outcome for a 1:1 fully redeemable stablecoin. If anyone is still asking you to pay a premium to buy USDC on Arc, treat it as a red flag.
Complete Steps for Cross-Chain Transfer of USDC to Arc Using Bitget Wallet
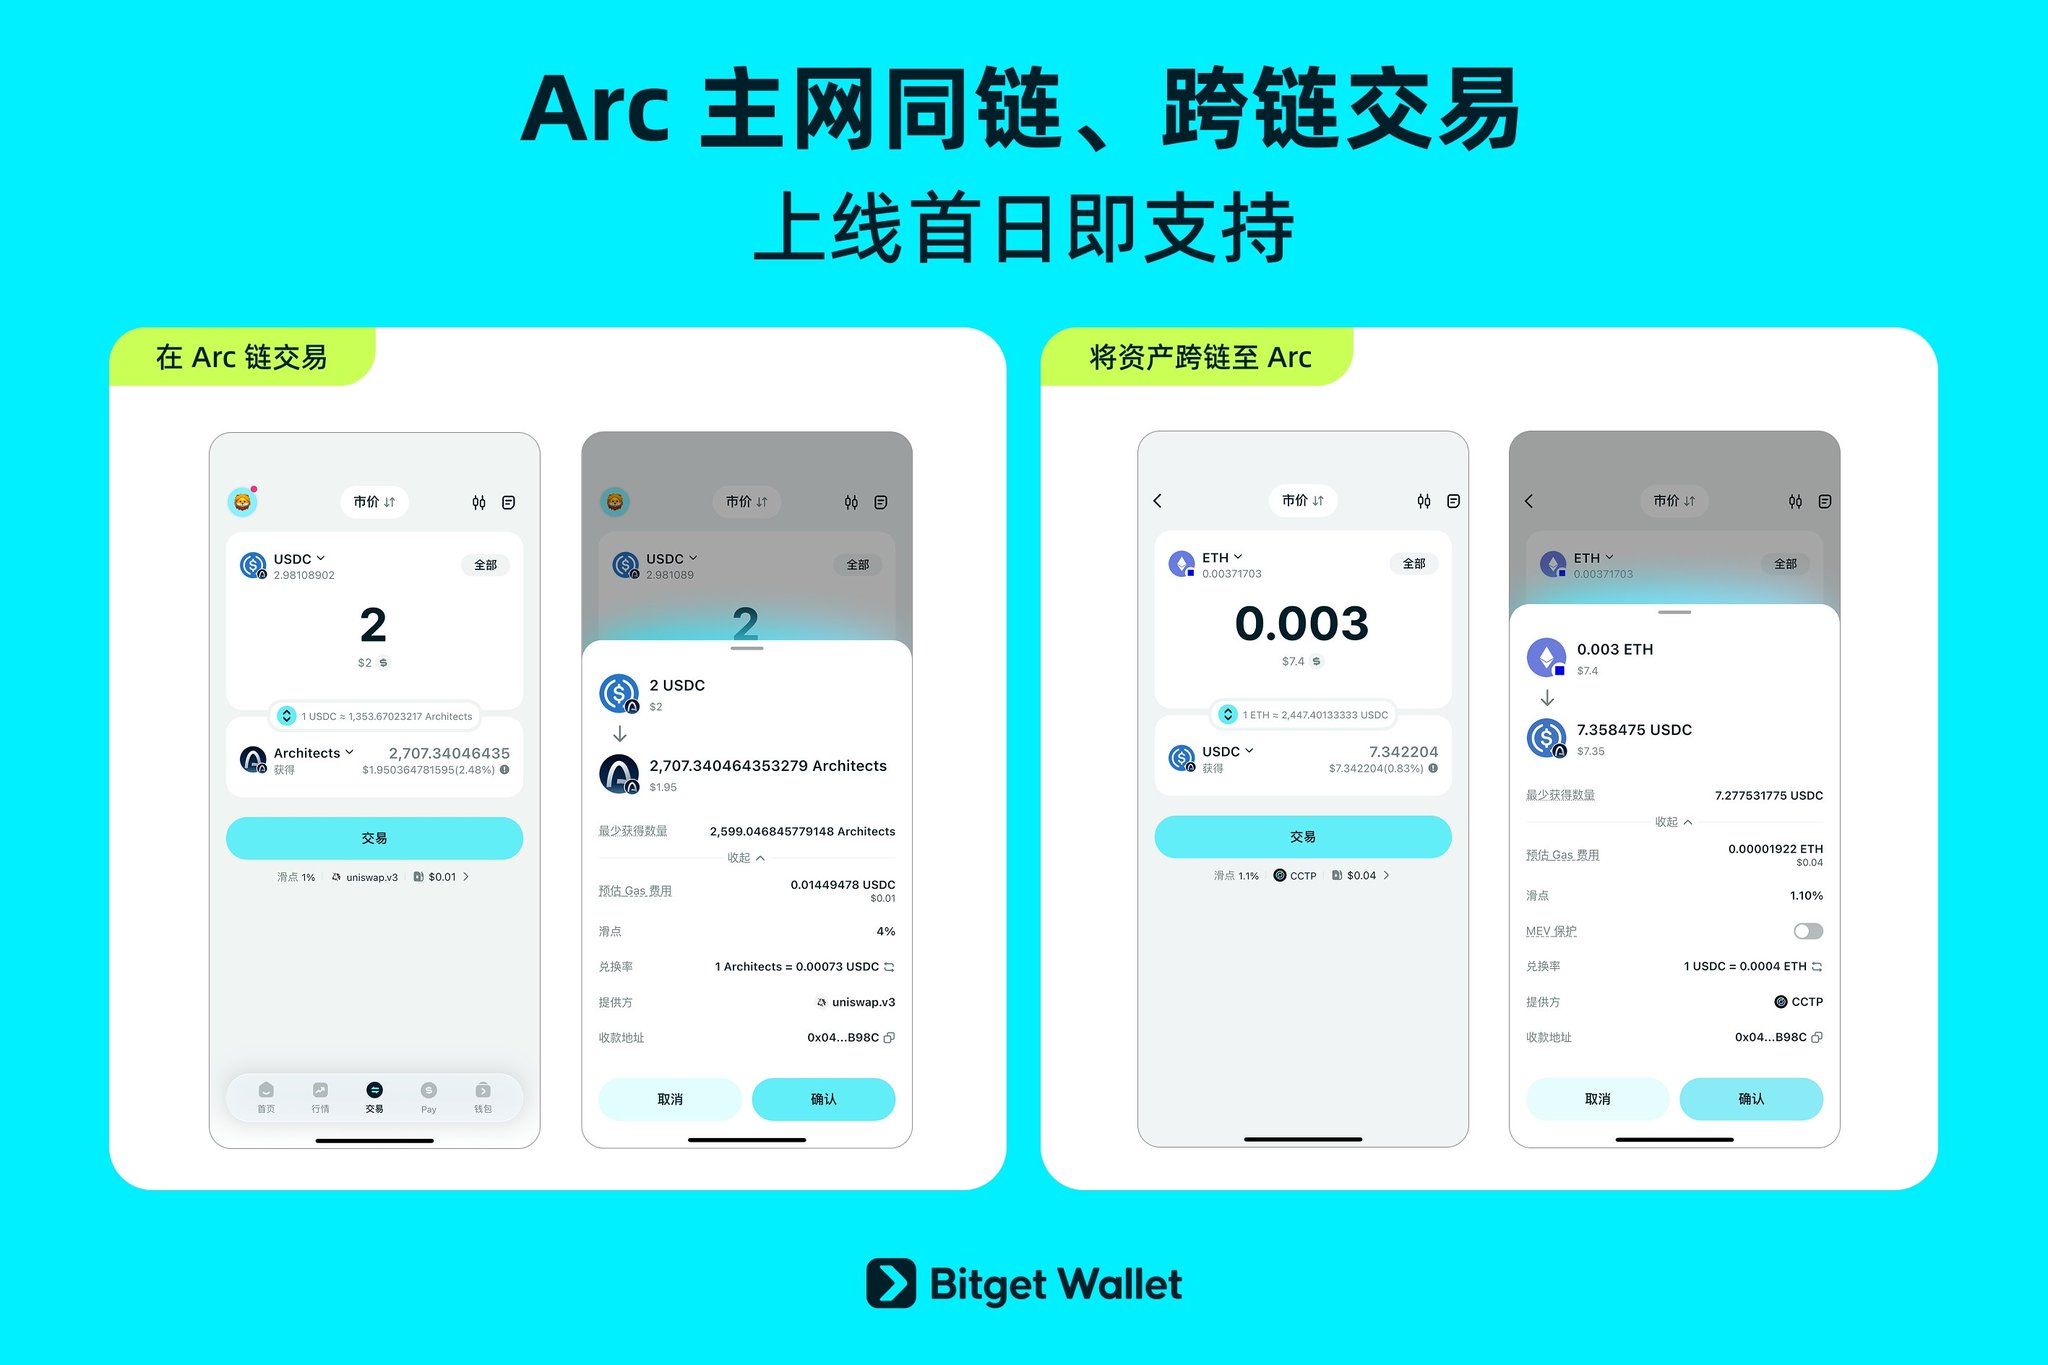
用 Bitget Wallet The benefits are clear: it comes with Arc’s official RPC built-in, so you can simply switch over and start using it right away. There’s no need to enter parameters manually, which eliminates the risk of entering the wrong RPC or mistaking one chain for another with the same name. On the first day, it already supported one-click transfers from over ten blockchains, including Ethereum, BNB Chain, and Solana. The process involves just six steps:
- Add Arc: Open Bitget Wallet, go to the Wallet page, tap the network icon in the upper-right corner, select Arc, and add it. Chain ID 5042 will be filled in automatically.
- Select a source: Tap "Trade" at the bottom, then select your existing chain and USDC from the options above.
- Select a destination: Select "Arc" and "USDC" below, then enter the amount.
- Review the details: The screen will display the exchange rate, estimated amount to be received, fees, slippage, and price impact. Carefully review each item.
- Send Transaction: Verify that your wallet balance is sufficient, then click "Confirm."
- Verifying the Deposit: Wait for Circle’s verification service to confirm the burn transaction on the source chain, which typically takes about one minute or more. Once the funds have been deposited, verify them on explorer.arc.io—do not rely solely on your wallet interface.
For your first transaction, be sure to start with a small amount—try it out with $20 to $50—to confirm that the funds are credited, can be spent, and can be converted back. Only then should you increase the amount. Once the funds are credited, you can use them immediately, since USDC itself serves as Arc’s gas; there’s no need to set aside separate tokens for transaction fees.
In terms of wallets, Circle’s official ecosystem list includes MetaMask, OKX Wallet, Binance Wallet, Rainbow, Zerion, Exodus, SafePal, and Ledger. Bitget Wallet also announced on its official account on September 11, 2026, that it would support the Arc mainnet on its first day, offering Swap, cross-chain, and dApp connectivity features. You can choose any of these; the key is to verify that the chain ID is 5042 when joining the network.
What if you don't have any USDC yet?
The most common starting point for Hong Kong readers is to first purchase major cryptocurrencies with Hong Kong dollars and then convert them. The typical process involves opening an account with a licensed brokerage firm to buy Bitcoin or Ethereum, withdrawing the coins to your own wallet, converting them to USDC, and finally bridging them to the target blockchain. If you don’t yet have this deposit and withdrawal channel, you can start by referring to Guide to Opening an Account with Futu Securities and Depositing/Withdrawing Cryptocurrency Establish a baseline path.
As for wallets, using a new blockchain like Arc requires a Web3 wallet that supports multiple chains and has built-in DEX and asset tracking features. This is much more reliable than manually adding RPC endpoints for each chain one by one using a browser extension. For complete setup instructions, see Bitget Wallet Tutorial。
What's in the Arc Ecosystem Now? A Three-Tiered Opportunity Map
The ecosystem on the first day of the Arc mainnet launch can be understood in three layers: the “pioneering layer” consisting of memes and launchpads, the “application layer” consisting of DeFi protocols, and the “long-term layer” consisting of tokenized assets and the ARC token itself. The risks, time horizons, and barriers to entry for these three layers are entirely different; conflating them is the most common mistake made by retail investors.
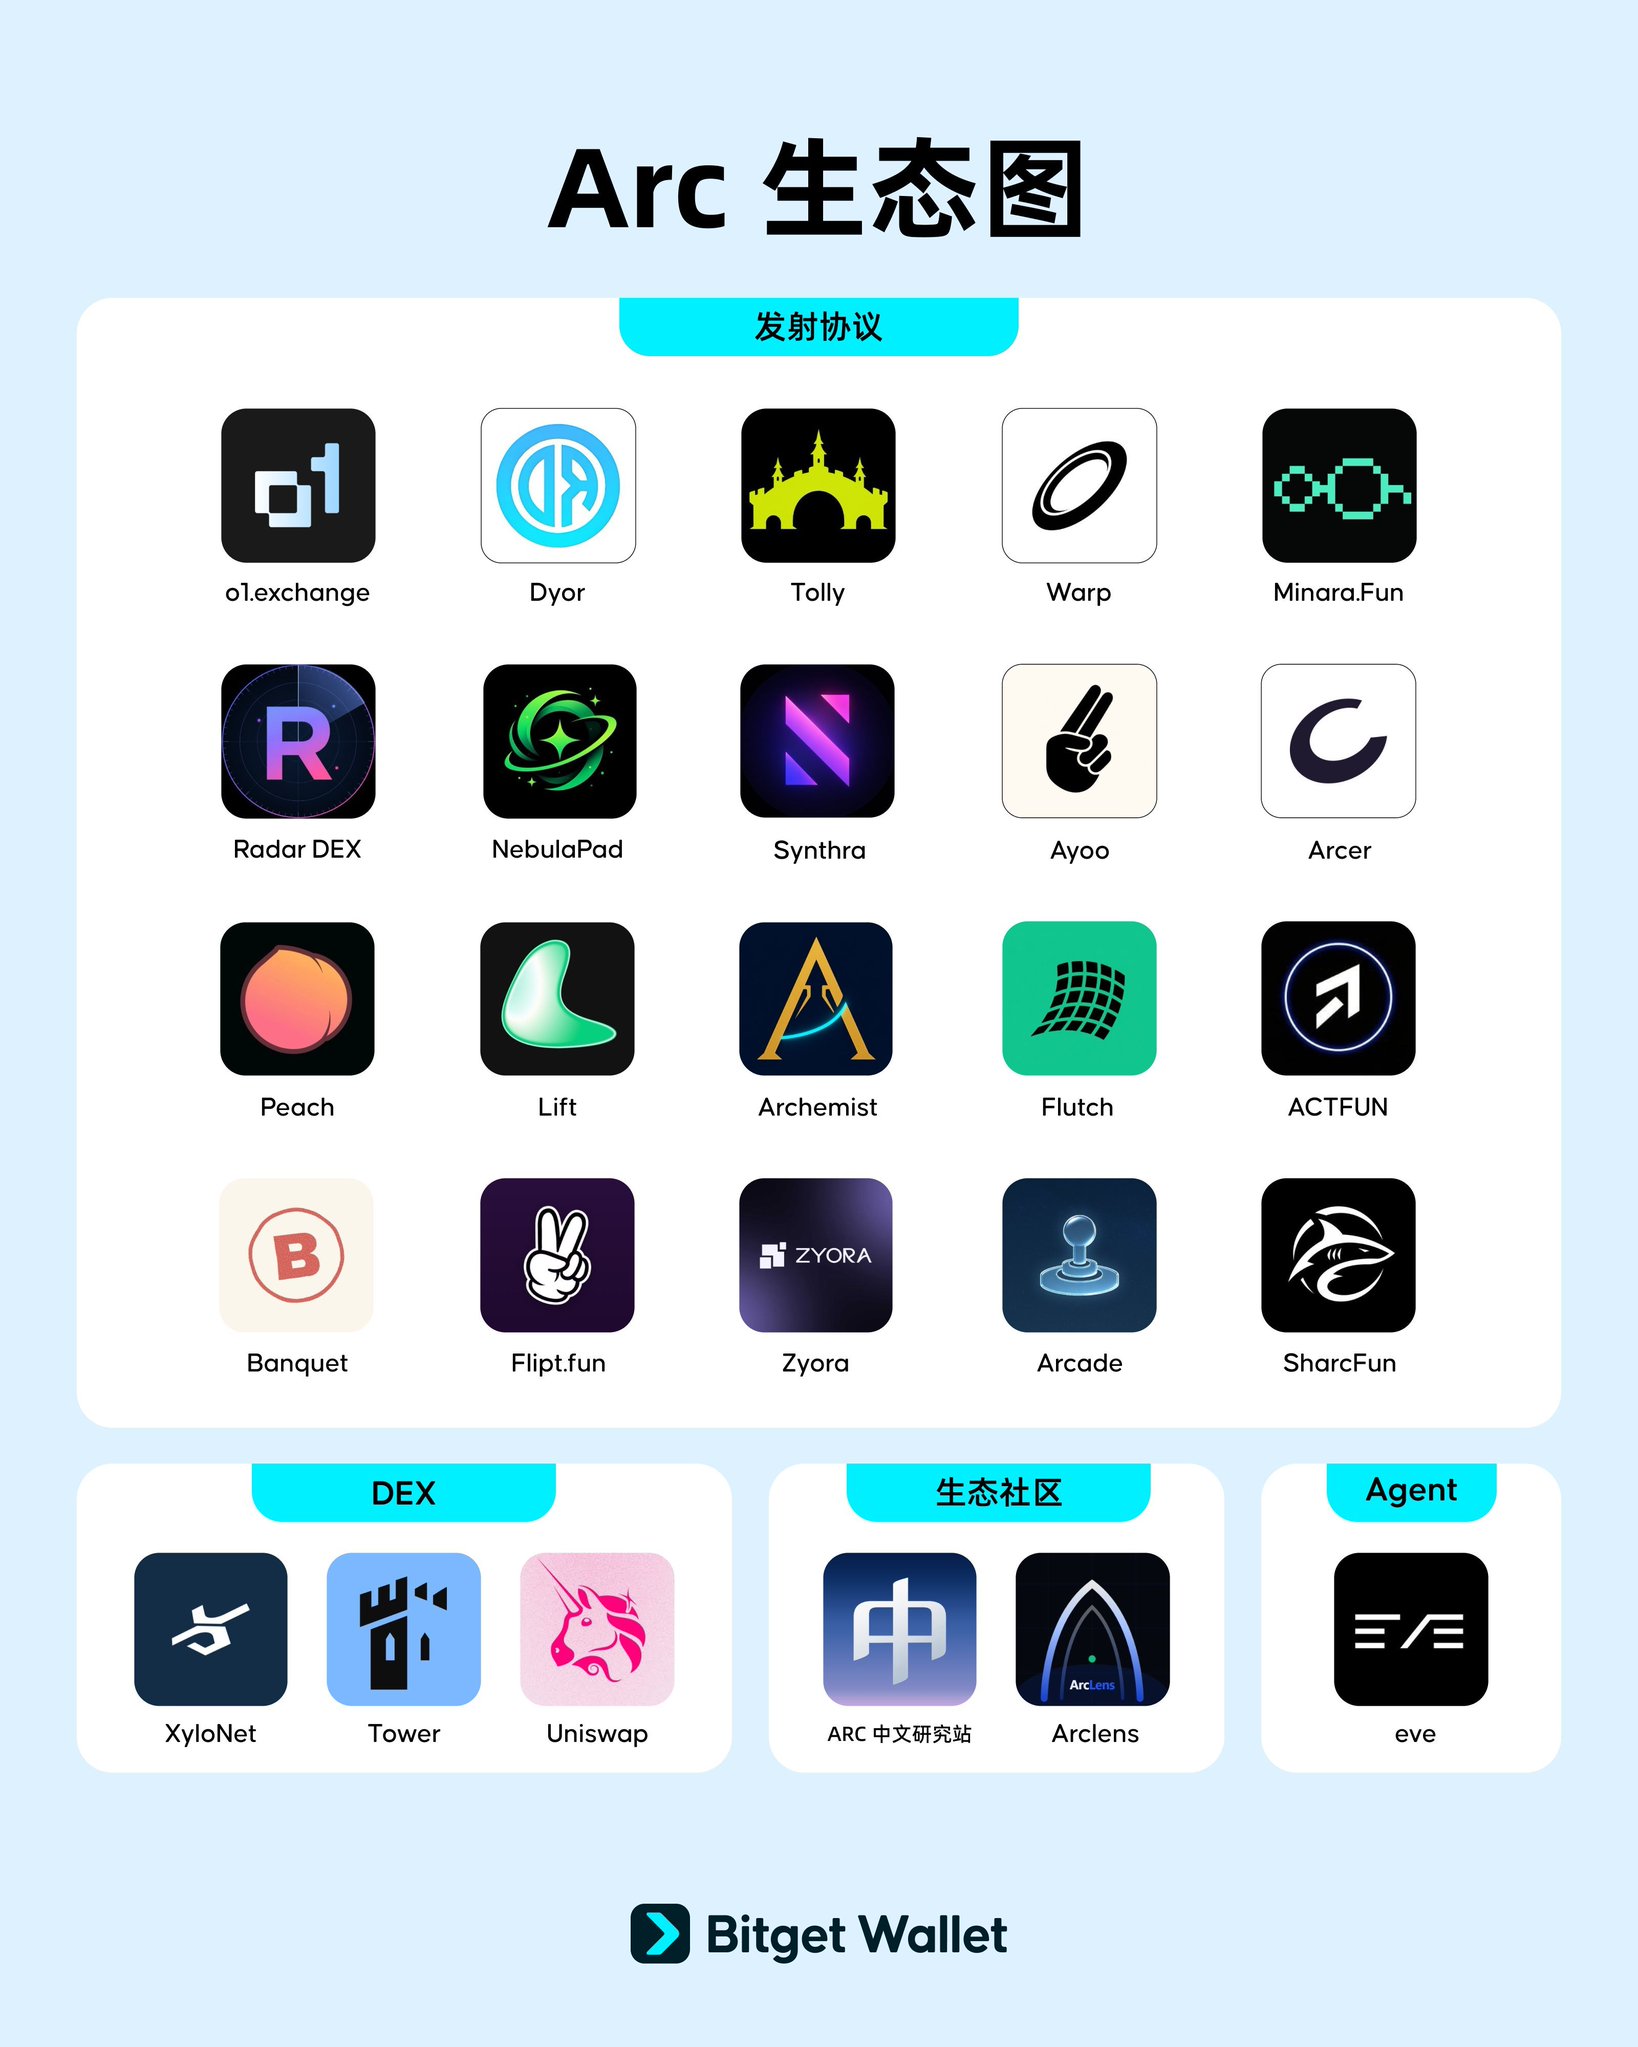
Pioneering Tier: The Race to the Launchpad Between Launchpads and Memes
Prior to the mainnet launch, a number of launchpads have already emerged on Arc’s private mainnet, competing for token issuance slots. Key players include: Tolly, which adopts a “no graduation system,” where the entire token supply is directly locked in a liquidity pool with USDC, with transaction fees of approximately 1%; Warp uses a “Bonding Curve” model; once its market cap reaches $69,000, it will migrate to its own DEX. It supports one-click cross-chain USDC purchases, has issued 288 tokens, and has recorded a cumulative trading volume of approximately $2.1 million.
The other three each have their own unique features: Long.supply maps tokenized stocks on the Robinhood Chain to Arc, with 487 tokens issued and the value of the cross-chain stock tokens totaling approximately $1.2 million; Archemist focuses on “social token issuance,” supporting token creation via an X Bot, with creators receiving an 80% fee share; trading volume totals approximately $468,000; ArcPad does not use a bonding curve; instead, it deploys directly to Uniswap V3 as one-sided liquidity, with the protocol and creators each receiving 0.5%.
As for leading meme projects, at the time of writing, COOL had a market cap of approximately $2.31 million to $2.94 million, Architects had approximately $820,000 to $2.79 million, and FatCatBatRatWifHat had approximately $1.16 million, and ARCAT at approximately $710,000 (data varies significantly across sources and changes rapidly; these figures are provided only to give a sense of the order of magnitude). But the number you really need to remember is another one:The liquidity of all top meme projects is below $106,000.. There is a severe disconnect between market capitalization and liquidity, meaning that most of the book value is illusory; even a moderately large sell order can break through the liquidity pool.
Application Layer: DeFi protocols launched on day one
The lineup of applications is clearly much more mature. On the lending side, there are Aave, Morpho, and Maple; on the trading side, Uniswap and Aerodrome; and Enso handles cross-chain onboarding—applications can use Enso to bring liquidity from other chains into Arc and directly execute swaps, deposits, loans, and leveraged strategies. On the trading side, Fomo, edgeX, and RadarDEX cater to liquidity demand.
There are also a number of utility projects: Tower Exchange serves as an aggregator; Hinkal Protocol provides a privacy layer; Orixa operates an NFT curation service and .arc domain names (purchasable with USDC); Arclens offers a project research tool; and ArcDEXScan provides a trading terminal. On the wallet and infrastructure side, support is already available from MetaMask, Binance Wallet, Ledger, Kraken, Fireblocks, and Chainlink.
For retail investors, the opportunity at the application layer lies not in “betting on which meme,” but in early-stage liquidity incentives. Yields from lending and market-making on new blockchains are typically significantly higher than on established blockchains during the first few months, offering a relatively quantifiable and controllable way to participate. If you’re unfamiliar with this type of stablecoin yield strategy, you can start by reading A Guide to Earning Interest on Stablecoins Establish a basic framework.
Long-Term Strategy: Tokenized Assets and RWA Deployment
The long-term layer is Arc’s true design goal. BlackRock’s BUIDL fund will be deployed to Arc; WisdomTree offers yield-generating tokenized investment funds such as WTGXX and CRDT; On the revenue side are Centrifuge, Superform, and Securitize—the latter has tokenized over $3 billion in assets and serves as an issuance partner for BlackRock BUIDL, Apollo ACRED, KKR, Hamilton Lane, and VanEck.
The market infrastructure is equally well-established: market makers and over-the-counter (OTC) traders include Auros, B2C2, Cumberland, Galaxy Digital, GSR, IMC, Keyrock, NONCO, Wintermute, and Zodia Markets; Custodians include BitGo, Copper, Taurus, and Zodia Custody, with Bank of New York Mellon (BNY) also exploring the space.
The time horizon at this level is measured in years, not weeks. It will determine whether Arc ultimately becomes the primary settlement venue for tokenized assets, and retail investors typically participate at this level not by buying on-chain memes, but by gaining exposure through RWA-related assets. To understand the full picture of this sector, see What Is RWA and Which Projects in This Space Are Worth Watching?。
What Makes Arc's Infrastructure Different? USDC as Gas, Sub-Second Finality, and the FX Engine
Arc’s technical architecture consists of three layers: the Malachite consensus engine, which provides deterministic finality in approximately 350 milliseconds; the Reth execution layer, which offers full EVM compatibility; and an institutional-grade foreign exchange engine built into the protocol layer. This combination is quite rare among existing public blockchains—most chains leave foreign exchange and privacy to the application layer, whereas Arc has chosen to integrate them into its infrastructure.
How does the Malachite consensus achieve sub-second finality?
Malachite is a high-performance implementation of the Tendermint Byzantine Fault Tolerance protocol developed by Informal Systems. Its key distinction from Nakamoto-style consensus lies in “determinism”: once a block receives signatures from more than two-thirds of the validators, it is immediately finalized and cannot be rolled back, with the entire process taking approximately 350 milliseconds to complete.
The premise of this design is that the number of validators must be controlled and their identities known—you cannot reliably count two-thirds of the signatures in a network where anyone can join anonymously. In other words, sub-second finality and a permissioned validator model are not two independent design choices, but rather two sides of the same technical trade-off. Any argument criticizing Arc’s centralization must also address the question: “Are you willing to give up deterministic finality?”
What does "Reth" stand for in the execution layer?
Arc’s execution layer is built on Reth, a Rust implementation of the Ethereum execution layer, and exposes the standard Ethereum JSON-RPC interface. In practical terms, this means that existing Solidity smart contracts can be deployed to Arc without any modifications; the full suite of Ethereum development tools—such as Hardhat, Foundry, and ethers.js—is immediately available; and wallets like MetaMask can connect directly.
This explains why the Arc ecosystem was able to attract more than 100 builders and protocols even before the mainnet launch. Developers don’t need to learn a new language or rewrite their contracts, so the migration cost is virtually zero. For a new blockchain, EVM compatibility is the most effective cold-start strategy.
How does the fee mechanism for using USDC as gas work?
Arc’s fee model is based on Ethereum’s EIP-1559, but instead of recalculating the base fee per block, it uses an exponentially weighted moving average of block utilization. Simply put, this slows down the response time of fee adjustments: short-term spikes in demand will not immediately drive up fees, and the fee curve becomes smoother and more predictable.
According to Arc Official DocumentationThe base fee for ERC-20 transfers is approximately $0.001, with a hard cap of 20,000 Gwei. The network has a gas throughput of 30 million per block, and under normal circumstances, the priority fee is close to zero. The average transaction cost observed during testnet testing was approximately $0.004.
There is one detail investors should keep in mind: Unlike Ethereum, Arc No-Burn Base Fee... The base fee and priority fee are paid in full to the block’s beneficiaries. This means that Arc does not follow the same “deflationary as usage increases” value accumulation path as Ethereum; the network’s economic value flows to validators rather than token holders. This point is crucial when evaluating the value of the ARC token.
What problems do the built-in FX engine and optional privacy features solve?
Arc has built an institutional-grade foreign exchange engine into the protocol layer, which includes an RFQ (Request for Quote) system for price discovery and 24/7 on-chain PvP (pay-per-pay) settlement. Settlement risk in traditional foreign exchange markets arises when one party has paid but the other has not delivered; PvP settlement binds the two transactions into an atomic operation, structurally eliminating this risk.
Another design feature is optional privacy: users and businesses can choose to hide their balances and transaction details. This is not intended to provide anonymity, but rather to allow businesses to meet their compliance obligations without having to fully disclose commercially sensitive information such as payroll, supply chain payments, and trading positions. For a blockchain aiming to attract institutional capital, a fully transparent ledger is actually a hindrance rather than a selling point.
Who Runs Arc Nodes? Founder Validators and the Costs of a Permissioned System
The list of Arc's founding validators is both the chain's biggest selling point and its biggest point of contention. According to Circle Official Press ReleaseThere are a total of 11 founding validators: BlackRock, DTCC, Galaxy, Global Payments, Intercontinental Exchange (ICE), Mastercard, MoneyGram, SBI Group, Standard Chartered Bank, Sumitomo Corporation, and Visa. Some media reports cite 12 validators; the official announcement should be taken as the definitive source.
Why is this list important?
This may be the most institutionally diverse group of genesis validators in the history of blockchain. BlackRock is the world’s largest asset management firm; DTCC is the core infrastructure for U.S. securities clearing; ICE owns the New York Stock Exchange; and Visa and Mastercard together process the vast majority of global card payments. The fact that these institutions are willing to operate nodes themselves signifies more than simply “investing in a project”; it means they are staking their own operational reputations on this blockchain.
A more concrete sign is the upcoming integration plans: BlackRock’s BUIDL tokenized money market fund will be deployed on Arc, while DTCC’s tokenization services are expected to be integrated in the second half of 2027. The latter is particularly worth noting—if DTCC does indeed move its custodied assets onto Arc, that will be the true watershed moment for the chain’s success or failure, rather than the mainnet launch on September 16 itself.
What is the cost of a permit-based verifier?
The criticism has been quite sharp. Adam Cochran, a partner at Cinneamhain Ventures, stated bluntly on X that Arc “is not a L1, and calling it that is an insult,” noting that under Circle’s design—which uses USDC as the root token— “there will never be an economic incentive to act as a loyal validator, which is why they had to make it a private consortium.” He described Arc as “a private consortium chain with pre-approved validators.”
This criticism is backed by concrete mathematical evidence. Under a Byzantine fault-tolerant consensus mechanism, in a network of twelve validators, it would take only four colluding validators to bring the entire network to a standstill, and eight to rewrite the ledger. Furthermore, these validators receive fees denominated in USDC, which is pegged to the U.S. dollar, meaning there is no economic counterbalance independent of the U.S. dollar system. If a regulatory authority were to order the freezing of a particular address, this structure leaves virtually no room for resistance.
How does the regulatory framework shape Arc's design?
Many of Arc’s design features are not the result of Circle’s free choice, but rather a direct consequence of regulatory requirements. The GENIUS Act, now in effect, imposes numerous obligations on stablecoin issuers; among these, anti-money laundering (AML) and know-your-customer (KYC) requirements are mandatory, which directly led to the implementation of a built-in blacklist mechanism at the protocol level. Meanwhile, the provision prohibiting the payment of interest is the reason why USDC—despite being a native Gas token—does not pay interest to its holders.
If the pending CLARITY Act is passed, it will provide a legal foundation for tokenized securities and the DTCC’s 2027 integration. However, there is a high degree of uncertainty surrounding this matter—at the time of writing, the odds of the bill passing on Polymarket were only about 16%. In other words, Arc’s most valuable long-term narrative currently hinges on a legislative outcome that is highly unlikely to materialize as scheduled. This is the variable most easily overlooked when evaluating Arc.
Will fiat-pegged stablecoins become the mainstream use case for Arc?
The most underrated narrative on Arc isn’t memes—it’s non-dollar fiat-backed stablecoins. Circle has launched StableFX and its Partner Stablecoin Program on Arc, with the first batch covering the Japanese yen (JPYC), South Korean won (KRW1), Canadian dollars (QCAD), Australian dollars (AUDF), Brazilian real (BRLA), Mexican pesos (MXNB), and Philippine pesos (PHPC), issued by JPYC, BDACS, Stablecorp, Forte, Avenia, Juno, and Coins.ph, respectively.
These assets are part of the same design as Arc’s built-in FX engine. With multi-currency stablecoins, combined with RFQ (Request for Quote) functionality and 24-hour PvP (Peer-to-Peer) settlement, Arc is able to facilitate true cross-border foreign exchange transactions. This is also the key distinction between Arc and the tokenized stock narrative of Robinhood Chain: the latter offers asset-backed securities, while the former provides a conduit for currency exchange.
For retail investors, the way to participate in this narrative is completely different from that of memes. Its value lies not in short-term price fluctuations, but in exchange costs: the implicit spread in traditional cross-border remittances is typically measured in percentage points, while on-chain peer-to-peer (P2P) settlements can reduce this cost to a level close to that of transaction fees. Markets with high remittance volumes, such as the Philippines, Mexico, and South Korea, are the most likely places to see early practical adoption.
Will Arc replicate the meme-driven price movements on the Robinhood Chain?
Most likely not. The Robinhood Chain meme craze at the time depended on four conditions all being met simultaneously, and Arc falls short on all four. Understanding this contrast is more valuable than chasing any single token.
What were the conditions for Robinhood Chain at the time?
First, the operator benefits directly—Robinhood itself profits from trading volume, so it has an incentive to drive excitement. Second, there is a ready-made retail channel—the app, with its tens of millions of users, directs traffic directly to the platform. Third, there are assets ripe for speculation. Fourth, a self-reinforcing cycle is created—rising prices attract more users, and more users drive prices higher.
Why Is Arc So Hard to Copy?
When compared item by item, Arc’s structure is exactly the opposite. At the operational level, the validators are institutions such as BlackRock, DTCC, and Visa; their reputational incentives run completely counter to meme speculation, making it impossible for them to endorse speculative fervor. On the retail access front, Arc does not have its own app or exchange front end; retail investors must find their own way in. In terms of the underlying asset, the ARC token has not yet been issued, so there is no core asset to fuel speculation. Regarding the ecosystem dynamics, the protocol’s design inherently suppresses MEV manipulation, making it difficult for a typical speculative flywheel to form.
A more practical limitation is liquidity. As mentioned earlier, liquidity for the top meme coins currently stands at less than $106,000. Even if a short-term rally occurs, prices at this level of liquidity are extremely fragile, and gains and losses can occur just as quickly. It is reasonable to view Arc’s pioneer tier as a “testing ground for small-scale experimentation,” but to characterize it as “the next Robinhood wealth effect” does not align with the structural realities.
ARC Tokens and Airdrops: What We Know, What We Don’t Know, and What We Shouldn’t Assume
As of this writing, the ARC token has not been publicly issued, and there are no airdrop plans officially confirmed by Circle. All “ARC airdrop guides” currently circulating online are based on community speculation. Distinguishing between disclosed facts and speculation is the first step in avoiding pitfalls.
What facts have already been disclosed?
Circle released the ARC white paper on May 11, 2026, and disclosed that it had completed a $222 million token private presale, at a fully diluted valuation of $3 billion, with a price of $0.30 per token and 740 million tokens allocated—representing approximately 7.4% of the initial supply of 10 billion tokens. This round was led by a16z crypto, with participation from institutions such as BlackRock, Apollo, and Intercontinental Exchange.
In terms of allocation, 60% is allocated to the ecosystem (covering token sales, developer grants, growth initiatives, and broader participation), while Circle retains 25%. ARC is positioned as the network’s coordination mechanism, supporting the transition from proof-of-license to proof-of-stake, governance, and fee distribution; validators will receive rewards in ARC derived from inflationary issuance and fee revenue.
Which key parameters remain unknown to this day?
There are more unknowns than knowns, and all of them are key factors in determining the price: the initial inflation rate, the decay curve, the unlock schedule, the dates of token generation events, listing plans, and whether there will be an airdrop and its rules—none of which have been disclosed yet. Circle’s statement is limited to “continuing to explore how the token can support incentives, governance, security, and utility.”
It is important to emphasize a point that is often misunderstood:The ARC token will not replace USDC as the gas token. Under the current design, USDC remains the asset used to pay transaction fees, while ARC serves the purposes of the validator economy and governance. Any valuation reasoning based on the premise that “ARC will become a source of gas demand” is inconsistent with the officially announced design.
How should we view expectations for airdrops?
There are indeed reward programs within the community, such as Arc House Rewards and Architects Rewards. Common ways to participate include claiming testnet tokens, deploying smart contracts, sending transactions, and minting NFTs. These activities involve no financial cost—only an investment of time—so they’re a perfectly acceptable way to get a foot in the door.
However, two things must be made clear: First, Circle has never confirmed a direct correlation between points and airdrops; second, in the absence of data on unlocking and inflation, any prediction of ARC’s listing price lacks a solid foundation. It is reasonable to view the airdrop as a “free call option,” but treating it as a “guaranteed return” is a misjudgment.
What are the risks to watch out for most with Arc?
The risk with Arc does not lie in whether “this chain will fail”—with BlackRock and Visa running nodes, the probability of a technical failure is very low. The real risk is that retail investors may mistakenly interpret the “success of institutional-grade infrastructure” as meaning “the assets they hold will appreciate in value,” even though there is no必然 relationship between the two.
Structural Risks: Centralization and Single Points of Censorship
A permissioned validation system implies that enforceable censorship capabilities exist at the network level. The protocol layer includes built-in blacklists, and validators’ identities are public and subject to regulation—design choices that serve as selling points for institutions but are a major drawback for users seeking to resist censorship. If your use case involves resisting censorship, Arc is not the right choice for you by design—this is not a flaw but a trade-off.
At the same time, validators’ financial incentives are denominated entirely in U.S. dollars, and there are no checks and balances independent of the U.S. dollar system. The fate of the entire blockchain is highly tied to Circle’s corporate survival and the direction of U.S. stablecoin regulation. This represents a centralized single point of failure that overlaps significantly with the risks associated with holding USDC itself.
Market Risk: Low Liquidity and Fake Underlyings
Liquidity in the early stages of an ecosystem is extremely limited, and the $106,000 liquidity cap mentioned earlier serves as the most direct warning. In addition, the launch period of a new blockchain is a time when scams are particularly prevalent: fake official websites, counterfeit coins with the same name, and malicious smart contract authorizations all tend to surface in large numbers. Verifying domain names, obtaining contract addresses only from official channels, and reviewing transaction details item by item before signing—these basic precautions are especially important during Arc’s first week of launch.
It’s also important to note that none of the assets currently tradable on the private mainnet have official endorsement, and Circle has not endorsed any ecosystem tokens. Transferring the trust associated with “Circle-branded” products directly to any meme or launchpad on the chain is a classic case of misjudging the brand’s halo effect.
Information Risk: Inconsistencies in Data Definitions
Transaction data for Arc’s testnet varies widely depending on the statistical methodology used, with figures ranging from over 100 million to 500 million transactions cited by different sources. These discrepancies stem primarily from differences in the statistical time periods considered and whether transactions on the private mainnet and public testnet are combined in the calculations. For readers, the key point is not which figure is correct, but rather that such figures are inherently unsuitable for assessing a blockchain’s actual usage.
The significance of this matter lies not only in the numbers themselves. It serves as a reminder that on a blockchain dominated by a single company—where early data was primarily released by that company—external verification channels are limited. To determine whether Arc is successful, we should look at independently verifiable metrics—actual capital inflows, the proportion of genuine settlement transactions, whether the initial economic parameters are disclosed as scheduled, and whether DTCC will actually complete the integration in the second half of 2027—rather than easily inflated figures like the number of on-chain transactions. If you want to track actual on-chain capital flows yourself, you can start by familiarizing yourself with Free On-Chain Tools to Track Fund Flows Basic Methods.
Frequently Asked Questions
Q: Do I need to buy ARC tokens to use the Arc public blockchain?
No, that’s not necessary. Arc uses USDC as its native gas token, and all fees are denominated in U.S. dollars. The ARC token has not yet been publicly issued; it is intended for validator incentives and governance, not for paying fees. Any claim that you must “buy ARC first to go on-chain” is unfounded.
Q: When will the Arc mainnet go live? Can I participate now?
The Arc public mainnet will launch on September 16, 2026. Prior to that, the network will be in the private mainnet phase, during which on-chain USDC must be obtained through over-the-counter markets at a premium of approximately 1.8 to 1, plus a fee of about 31 TP3T. We recommend waiting until the public mainnet and the official cross-chain bridge are launched before entering the market at normal costs.
Q: Will there be an airdrop on the Arc public blockchain?
Circle has not confirmed any airdrop plans to date. The existing Arc House and Architects points are part of community initiatives, and the official team has never clarified the relationship between these points and airdrops. Since the inflation rate, unlock schedule, and token generation event dates have all been undisclosed, any predictions regarding the value of airdrops lack a basis.
Q: Is Arc a truly decentralized blockchain?
No. Arc uses a permissioned validator model, with 11 founding validators selected by Circle and a built-in blacklist at the protocol level to meet regulatory requirements. Under a Byzantine fault-tolerant consensus mechanism, a small number of colluding validators can influence the network. Arc trades for deterministic finality and institutional compliance at the cost of sacrificing its permissionless nature.
Q: What is the most reasonable way for retail investors to participate in Arc?
There are three tiers based on risk tolerance. The “Pioneering Tier” includes memes and launchpads with liquidity below $106,000, which are only suitable for small-scale test runs. The “Application Tier” features early-stage DeFi liquidity incentives that are relatively quantifiable, making it a more conservative choice. The “Long-Term” tier—which includes RWA and ARC tokens—operates on an annual time scale and requires patience rather than speed.
Q: What are the key indicators of Arc's success?
The key issue is not the mainnet launch on September 16, but whether the DTCC will actually complete the integration of tokenized asset custody in the second half of 2027. Until then, we should focus on whether the initial economic parameters have been disclosed, the actual volume of capital inflows, and the proportion of genuine settlement transactions—rather than the number of on-chain transactions.
Next Step
The Arc public blockchain combines two distinct roles—"institutional-grade settlement infrastructure" and "early-stage on-chain investment platform"—on a single chain, even though these two roles differ entirely in terms of time horizons, risk profiles, and participation models. The truly important decision isn’t “whether to enter the market,” but “which layer you want to participate in”—using confidence in the long-term layer to justify positions in the early-stage layer is the most common mistake in this cycle.
If you decide to try Arc for yourself, start by setting up a multi-chain Web3 wallet and keep your initial USDC deposit to an amount you wouldn’t mind losing entirely. Next, you can read more here What Is RWA and Which Projects in This Space Are Worth Watching?, to understand the specific market segment Arc has been truly competing for in the long term.